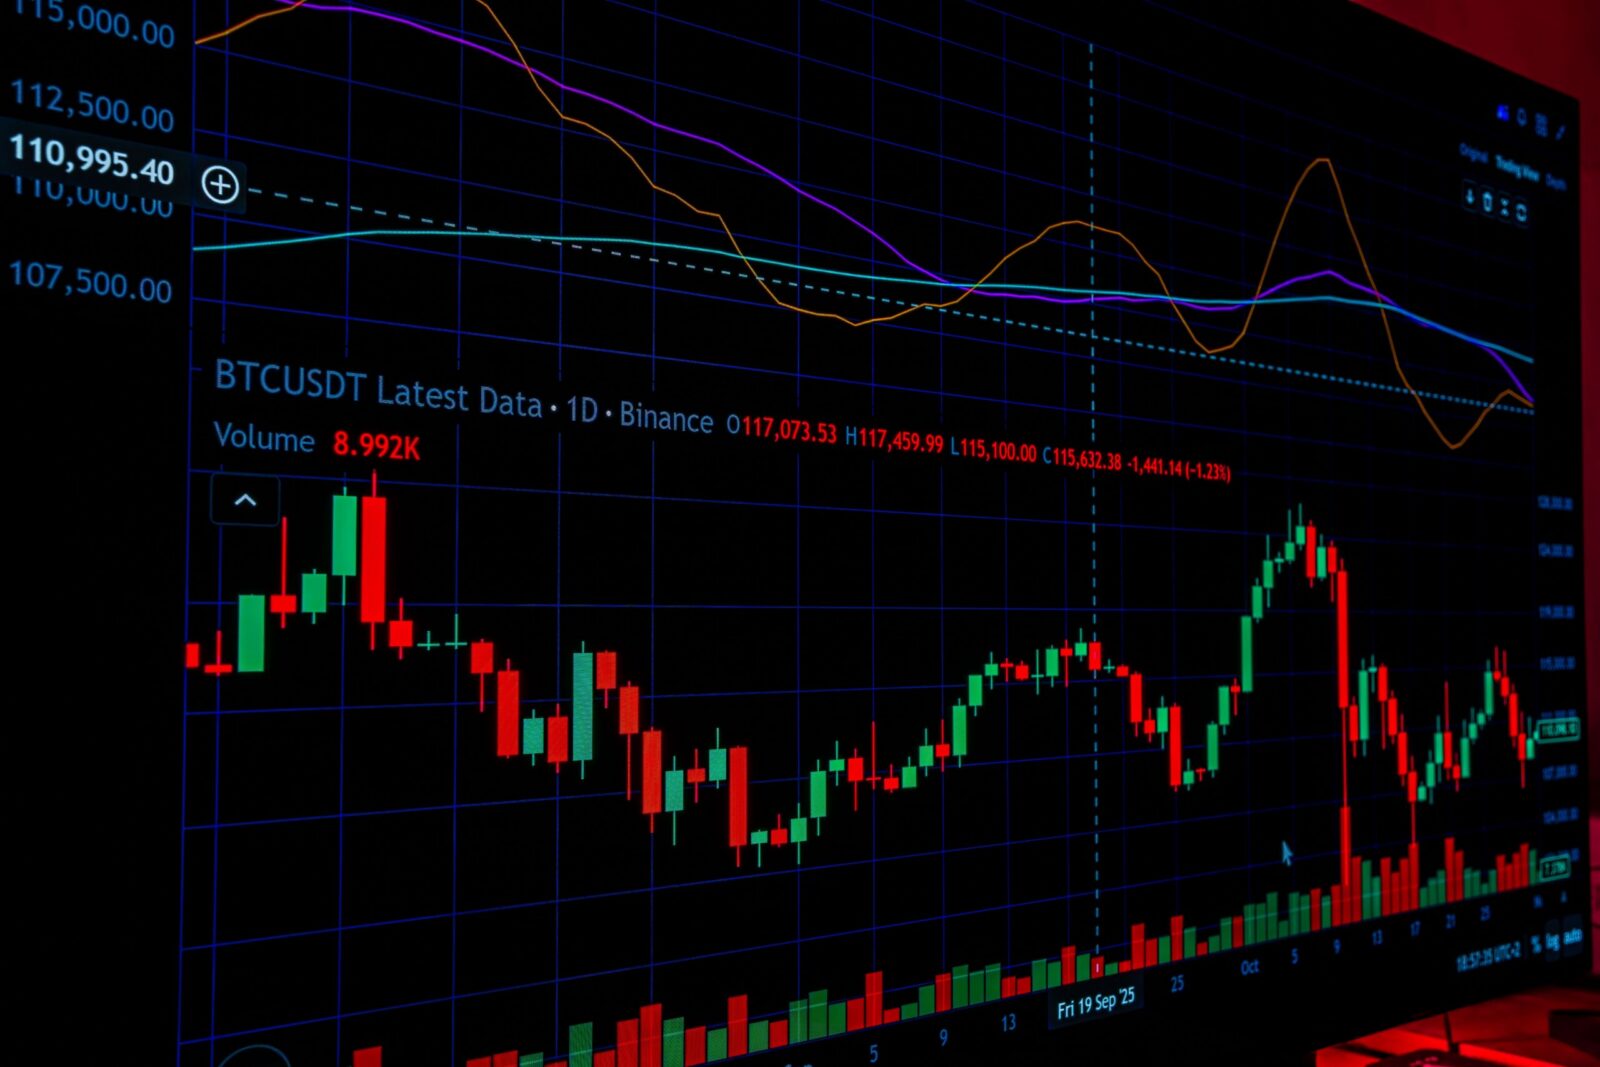
Cryptocurrency, digital wallets, and nonfungible tokens can be property subject to disclosure and division in a California divorce. Their decentralized nature and price volatility can make identification, characterization, and valuation more complicated than with a traditional bank account.
Digital Assets Must Be Disclosed
Each spouse must disclose assets in which either spouse or the community may have an interest. This obligation is not limited to assets listed on standard financial schedules.
Relevant assets may include cryptocurrency, digital-wallet balances, exchange accounts, NFTs, staking rewards, token distributions, and other digital holdings. A spouse should not omit an asset merely because it is held anonymously or outside a conventional financial institution.
Transaction Histories Can Help Trace Ownership
The court may need to determine when the asset was acquired and what funds were used. Digital-wallet transaction histories, exchange statements, purchase confirmations, bank transfers, tax records, and records showing transfers between wallets may be important.
An asset acquired before marriage or with separate funds may be separate property. Purchases made with marital earnings during marriage are generally subject to the rules governing community property.
Mixed transactions may require tracing to distinguish community and separate interests.
Valuation Can Change Rapidly
Digital assets may fluctuate substantially between separation, disclosure, settlement, and trial. The parties should identify the type and quantity of each asset and the date and source used for valuation.
Some tokens may have limited markets, transfer restrictions, or disputed ownership rights. An NFT’s advertised price does not necessarily establish what a buyer would actually pay.
The court also may need to consider transaction costs, access limitations, and immediate tax consequences supported by the evidence.
Secure Division Requires Careful Planning
A settlement or judgment should explain whether the asset will be transferred, sold, or awarded to one spouse with an equalizing payment. It should also address exchange restrictions, wallet access, transaction timing, and confirmation that the transfer was completed.
Neither spouse should transfer or conceal digital assets in violation of fiduciary duties, disclosure requirements, or automatic restraints.
A California property division attorney working with a qualified financial professional can trace digital transactions, obtain a defensible valuation, and structure a secure division.
No responses yet